Internship Stipend Tax If you completed an internship and noticed 10% missing from your stipend when it landed in your account, there’s a good chance you assumed that money was simply gone — a cost of doing the internship, the same way tax gets deducted from any paycheck without a second thought. Here’s what most students in exactly this situation don’t realize: if your total income for the year falls below the taxable threshold, that deducted tax isn’t lost. It’s sitting in the government’s system under your PAN, refundable in full, but only if you actually file a return to claim it. Most students never do, either because they assume filing a return only applies to people who owe tax, or because they’ve never been told this deduction is genuinely reversible.
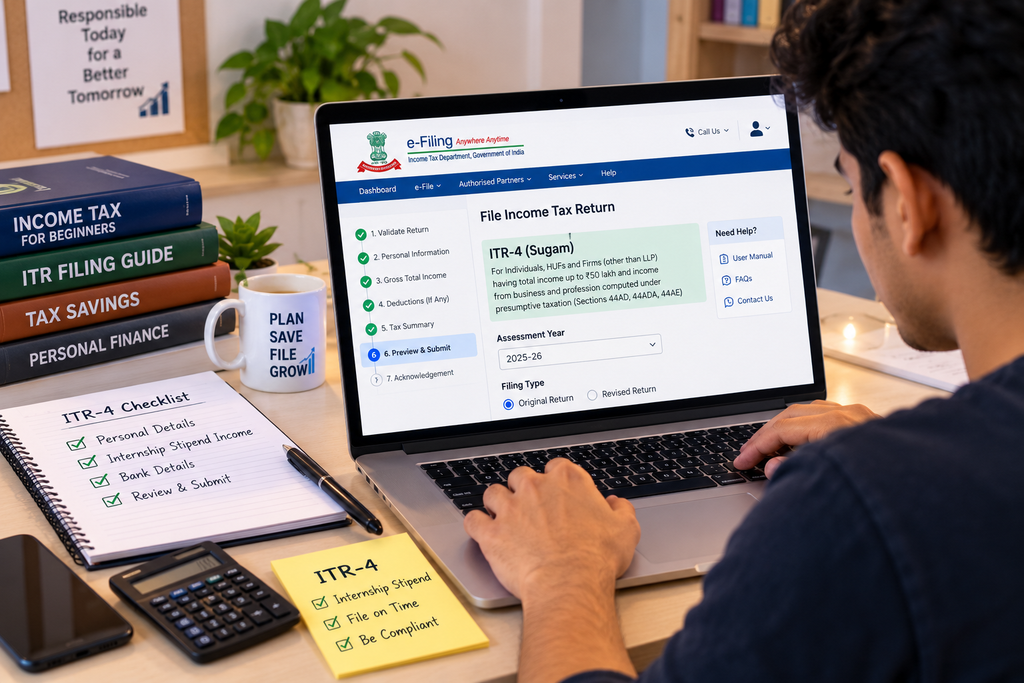
This guide covers how internship stipends are actually classified under Indian tax law — which turns out to be more complicated than most casual advice suggests — the specific threshold that determines whether tax gets deducted in the first place, and exactly how to claim back money that’s rightfully yours, using the exact same government portal you’d use for any other income tax filing.
Table of Contents
Stipend Isn’t One Thing Under the Law — It’s Three Different Things
This is the part almost no casual explanation gets right,Internship Stipend Tax and it’s worth understanding clearly before anything else, since it determines everything downstream — whether you owe tax at all, whether you get any deductions, and which tax form you’d even use.
Bucket one: a genuine scholarship, fully exempt under Section 10(16). If the payment is specifically meant to help you meet the cost of pursuing an education or qualification, rather than functioning as payment for services you performed, it’s treated as a scholarship and is completely tax-free, with no upper limit on the amount. This isn’t just a theoretical category — a genuine court precedent, A. Ratnakar Rao vs. Additional CIT, decided by the Karnataka High Court, specifically held that a stipend paid to a doctor for furthering their education and training qualifies as a scholarship and is tax-exempt. This bucket generally applies to research fellows (JRF/SRF) and PhD students specifically.
Bucket two: salary, taxed under Section 192, if a genuine employer-employee relationship exists. If your internship functions essentially like an employment relationship — set hours, direct supervision, ongoing work assigned as part of the organization’s regular operations — your stipend may be classified as salary, which comes with standard deductions available and gets reported under “Income from Salary.”
Bucket three: professional fees, taxed under Section 194J — where most company internships actually fall. If there’s no formal employer-employee relationship, which describes most short-term company internships, your stipend is typically treated as payment for professional services. This gets taxed under “Income from Other Sources,” and critically, no standard deduction and no expense set-off is allowed against this specific category of income — a real, meaningful disadvantage compared to the salary bucket, since you can’t offset this income the way a genuine employee could.
Which bucket your specific stipend falls into isn’t something you get to choose — it depends on the actual nature of your arrangement, and it determines everything about how you’d handle the tax side of your specific internship, from which form you file to whether you get any deductions at all against that income.
The Specific Threshold That Triggers TDS in the First Place
Under Section 194J, a company is required to deduct TDS at 10% if it pays a “professional” — which, for tax purposes, includes most interns falling into bucket three above — more than ₹30,000 during a single financial year. This is the specific number that determines whether you see any deduction at all on your stipend.
Here’s a detail worth knowing precisely, since it affects how you might plan multiple internships across a year: this ₹30,000 threshold applies per individual payer, not against your combined total income across all sources. If Company A pays you ₹28,000 for one internship and Company B separately pays you ₹28,000 for a different internship within the same financial year, neither company is required to deduct any TDS, even though your combined stipend income across both totals ₹56,000. Each payer evaluates the threshold independently, based only on what it itself paid you.
Why “Tax Was Cut” Doesn’t Mean “Tax Is Owed”
This is the core point worth internalizing clearly: a 10% TDS deduction under Section 194J is not a final tax assessment — it’s an advance, provisional deduction that gets reconciled against your actual total tax liability once you file your return. If your total taxable income for the year — including your stipend and anything else you earned — falls below the basic exemption threshold (roughly ₹7 lakh under the current new regime, once you factor in the applicable rebate under Section 87A), your actual computed tax liability is zero, regardless of how much TDS was deducted throughout the year. When you file your return in this situation, the system calculates your genuine tax owed as nil, and shows a “Refund Due” amount exactly equal to whatever TDS was deducted — which the government is then obligated to return to you.
How to Actually Claim This Refund
The process is more straightforward than most students assume once you understand the underlying mechanism:
- File your Income Tax Return, even if you believe you don’t technically owe any tax. Filing isn’t mandatory if your gross total income sits below the exemption threshold, but doing so voluntarily is the only way to actually claim back TDS that’s already been deducted — skipping this step means the deducted amount simply stays with the government indefinitely.
- Use the correct ITR form for your situation. Income taxed under Section 194J (bucket three above) is generally reported using ITR-4, provided you’re not maintaining formal books of account and are willing to declare a minimum of 50% of your gross receipts as income under the presumptive taxation scheme — a simplified filing route many students in this exact situation are eligible to use.
- Enter your total income accurately, including your stipend and any other income sources for the year.
- Let the portal calculate your actual liability. If your genuine computed tax comes out to zero given your total income, the system will show your refund due, matching the TDS amount already deducted.
- Ensure your bank account is properly validated on the income tax portal, since refunds are credited directly via this route — an unvalidated account is a common, avoidable reason refunds get delayed.
The Detail Almost Everyone Misses: Other TDS You Didn’t Even Know About
Here’s a genuinely easy-to-overlook scenario worth checking for directly: even if your actual stipend falls into the fully tax-exempt scholarship bucket described above, you can still have other TDS sitting unclaimed in the system under your own PAN — most commonly, a bank deducting 10% TDS on interest earned from a fixed deposit, particularly one funded by money gifted from parents or grandparents. This TDS is genuinely refundable using the exact same mechanism described above, but only if you actually file a return covering that income too. It’s worth checking your Form 26AS or Annual Information Statement on the income tax portal directly, since these documents show every instance of TDS deducted against your PAN across all sources — not just your internship stipend specifically — before assuming you have nothing at all worth claiming back this year.
Why the Bucket Matters Beyond Just the Tax Rate
It’s worth being clear about why correctly identifying which of the three buckets your stipend falls into matters beyond simply understanding your tax rate. If your stipend is genuinely a scholarship (bucket one), it’s completely exempt regardless of amount, and you’re not required to file a return at all unless you want to voluntarily document it or claim back unrelated TDS as described above. If it’s salary (bucket two), you get access to the standard deduction, which genuinely reduces your taxable income before any tax calculation even begins. If it’s professional fees (bucket three) — the most common category for company internships specifically — you get no standard deduction, meaning your entire stipend amount, minus only any Chapter VI-A deductions you’re separately eligible for (such as 80C investments), forms your taxable base for that income. Correctly identifying your actual bucket, rather than assuming a favorable one, is worth doing carefully rather than guessing.
What About Internships Abroad?
If your internship was based outside India, it’s worth knowing that a Double Taxation Avoidance Agreement (DTAA) between India and the country where you interned can exempt you from paying tax twice on the same income — for instance, income from a US-based internship benefits from the specific tax treaty between India and the United States. It’s also worth being direct about a related point: some students and employers have historically tried labeling a stipend as a “living allowance” specifically to avoid tax treatment, but this kind of relabeling doesn’t actually change how the payment is assessed — tax authorities look at the genuine underlying nature of a payment, not simply the word used to describe it, so treating a stipend as an “allowance” doesn’t itself create a valid basis for exemption if the underlying payment is genuinely compensation for services performed.
Why Companies Rarely Explain Which Bucket Your Stipend Falls Into
It’s worth understanding why this classification question often goes completely unaddressed during your actual internship, rather than assuming this is deliberately withheld information. Most companies structure their internship programs around administrative and legal simplicity rather than tax optimization for the intern specifically, and HR or finance teams processing your stipend typically apply whatever standard classification their payroll system defaults to for non-employee, short-term engagements — which is very often the professional-fees route under Section 194J, regardless of whether a more favorable classification might genuinely apply to your specific situation. This isn’t necessarily a deliberate choice to disadvantage you — it’s often simply the path of least administrative complexity for a company managing many short-term interns simultaneously. If you believe your specific internship arrangement more genuinely resembles an employer-employee relationship (set hours, direct supervision, ongoing assigned work) rather than an independent professional engagement, it’s reasonable to raise this directly with your internship coordinator or HR contact, though the final classification decision ultimately rests with how the company has structured the engagement, not with your own preference.
A Common Misconception Worth Correcting: Your Offer Letter’s Wording Doesn’t Decide This
A specific misconception worth addressing directly: some students assume that whatever their internship offer letter calls the payment — “stipend,” “honorarium,” “training allowance” — determines its tax treatment. It doesn’t. As covered above regarding the “living allowance” relabeling issue, tax authorities assess the genuine substance of the payment and the underlying working relationship, not the specific word chosen in your offer letter. A payment labeled “stipend” that functions exactly like salary in practice can still be assessed as salary income, and a payment labeled something more formal-sounding can still be assessed under whichever bucket its actual nature genuinely fits. Don’t assume your offer letter’s specific wording settles the tax question on its own — the classification depends on the real, functional nature of your specific arrangement.
A Practical Way to Approach Multiple Internships Across a Year
If you’re planning to take on more than one internship within the same financial year, it’s worth thinking through the tax implications proactively rather than discovering them only once TDS shows up unexpectedly on one specific stipend payment. Track your cumulative stipend income across all sources for the year, understand which bucket each specific internship likely falls into based on its actual working arrangement, and keep records — offer letters, stipend payment confirmations — for each engagement, since these help substantiate your income sources clearly if you’re filing a return covering multiple internships together. If a specific internship’s total payment is likely to cross the ₹30,000 threshold with a single employer, expect TDS to apply and plan your filing accordingly, rather than being surprised by a smaller-than-expected stipend credit.
Why This Also Matters for Your Broader Financial Record
Beyond the immediate refund itself, filing a return during your internship years, even a simple one covering a modest stipend, has a genuine secondary benefit worth knowing about: it begins building a documented financial history under your own PAN, independent of your parents or guardians. This can matter meaningfully later when you’re applying for your first credit card, a personal loan, or even a rental agreement that asks for income tax return copies as part of standard documentation — having a filing history that goes back to your student years, however modest the income involved, is a small but genuine advantage over having no filing history at all until your first full-time salaried role begins.
Why This Is Worth Doing Even for a Small Refund Amount
It’s reasonable to wonder whether filing a full return is genuinely worth the effort for what might be a modest refund — a few thousand rupees of TDS deducted from a single internship stipend. It’s worth reframing this slightly: the actual filing process, once you understand which ITR form applies and have your income details ready, generally takes well under an hour for a straightforward single-stipend situation, and the online portal walks you through the presumptive taxation calculation with pre-filled data pulled directly from your Form 26AS in most cases. Relative to that modest time investment, recovering money that’s rightfully yours — rather than leaving it with the government simply because claiming it felt like more effort than it was worth — is a genuinely favorable trade, and it also builds a filing habit that serves you well once your income grows and filing becomes a more clearly mandatory, higher-stakes annual task.
Quick Answers
If TDS was deducted from my internship stipend, is that money gone forever? No, if your total income for the year falls below the taxable threshold, you can file a return and receive a full refund of the TDS deducted.
What are the three ways a stipend can be classified under Indian tax law? As a tax-exempt scholarship under Section 10(16), as salary under Section 192 if a genuine employer-employee relationship exists, or as professional fees under Section 194J, which is where most company internships fall.
At what amount does a company have to deduct TDS on my stipend? If a single payer pays you more than ₹30,000 in a financial year, they’re required to deduct 10% TDS under Section 194J — and this threshold applies per payer, not your combined income across multiple sources.
Which ITR form should I use if my stipend is taxed under Section 194J? Generally ITR-4, using the presumptive taxation scheme, provided you’re not maintaining formal books of account and are willing to declare at least 50% of your gross receipts as income.
Do I get a standard deduction on stipend income taxed as professional fees? No, income under this specific category doesn’t allow a standard deduction or expense set-off, unlike stipend income classified as salary.
Can I claim a refund even if I don’t think I owe any tax at all? Yes, filing a return is actually the only way to claim back TDS that’s already been deducted — not filing means the deducted amount stays with the government even though you owed nothing.
Is a research fellowship stipend taxed the same way as a company internship stipend? Not necessarily — a genuine scholarship, such as many research fellowships, is fully exempt under Section 10(16), while most company internships, lacking a formal employer-employee relationship, are more commonly taxed under Section 194J as professional fees instead.
One More Thing Worth Checking Before You File
Before submitting your return, it’s worth doing one final cross-check: compare the TDS figure your employer reported against what actually shows up in your own Form 26AS on the income tax portal. Occasionally, a company deducts TDS correctly but delays or fails to properly deposit and report it against your PAN, which means the amount shown in your own tax records doesn’t yet match what was actually withheld from your stipend payment. If you notice this kind of mismatch, it’s worth raising it directly with your former internship employer’s finance or payroll team before filing, since claiming a refund based on TDS that hasn’t yet been properly reported against your PAN can create processing delays or discrepancies that take longer to resolve than simply catching the issue upfront.
If you’re filing your first return covering internship income, our guide on ITR Deadline 2026 covers the broader filing mechanics and deadlines relevant to any first-time filer, and our piece on Gig Worker Social Security 2026 is worth reading if you’re also doing freelance or platform-based work alongside a formal internship, since both involve similar “not classified as a standard employee” tax and benefit implications — together, these guides give you a genuinely complete picture of how non-traditional income sources are treated under current Indian tax and labour law.
Suggested Internal Links
- Internships Category
- ITR Deadline 2026: Worse Than Just a Late Fee
- Gig Worker Social Security 2026: What You Actually Get
Suggested External References
- Income Tax Department e-Filing Portal: https://www.incometax.gov.in
- Central Board of Direct Taxes (CBDT): https://www.incometaxindia.gov.in
- National Career Service Portal (India): https://www.ncs.gov.in